

A House in Multiple Occupation can earn far more than the same property let to one family, but it comes with licensing, planning rules and a lender market of its own. Landlords who get the numbers and the paperwork right do well. Those who treat an HMO as a bigger buy-to-let tend not to.
This page explains how HMO finance works, alongside what counts as an HMO, the licensing and planning rules, the costs and income to expect and day-to-day management. For lender criteria, rates and calculators, it points you to the pages that go deeper.

Buying or refinancing an HMO? Speak to a specialist before you apply.
What Counts as an HMO
A property becomes an HMO when three or more people from different households live in it and share a kitchen, bathroom or toilet. A family, including a couple, counts as one household, while unrelated sharers each count separately.
Councils split HMOs into two broad groups. A large HMO has five or more occupants from at least two households. A small HMO has three or four. The group decides which licence applies, and it also changes how lenders look at the deal. Student houses, professional house shares and converted properties are the usual examples.
HMO Licensing and Planning
Licensing is the first thing to check, because it affects whether you can let the property, whether you can borrow against it and what happens if you get it wrong.
In England, an HMO needs a mandatory licence once five or more people from at least two households live there, however many floors it has. Many councils also license smaller shared houses of three or four people, and some run selective licensing for other rented homes in designated areas. Scotland and Wales have separate rules, and the local council can confirm the position.
A licence application normally asks for:
- Floor plans of the property
- Gas and electrical safety certificates
- Proof that fire safety measures are installed
- Proof that room sizes and amenities meet the council’s standards
- The licence fee, which is set by each council and often runs from several hundred pounds to over £1,000
A licence usually lasts up to five years. Letting without a required licence can bring a civil penalty of up to £30,000 per offence, an unlimited fine on prosecution and rent repayment orders of up to 12 months’ rent.
Planning is separate from licensing. Changing a standard home (use class C3) to a small HMO for three to six sharers (C4) is normally permitted development in England, but many councils have removed that right through an Article 4 Direction, and a planning application is then needed. Larger HMOs for seven or more people need planning permission in every case. Check both before you commit to a purchase, because a property you cannot get consent for is hard to value or finance.
Bedroom size is regulated as well. The national minimum for a single adult’s bedroom is 6.51 square metres, and some councils require more kitchens and bathrooms as occupant numbers rise.
HMO Costs and Running Expenses
Set-up costs are higher than for a standard let. Typical items include:
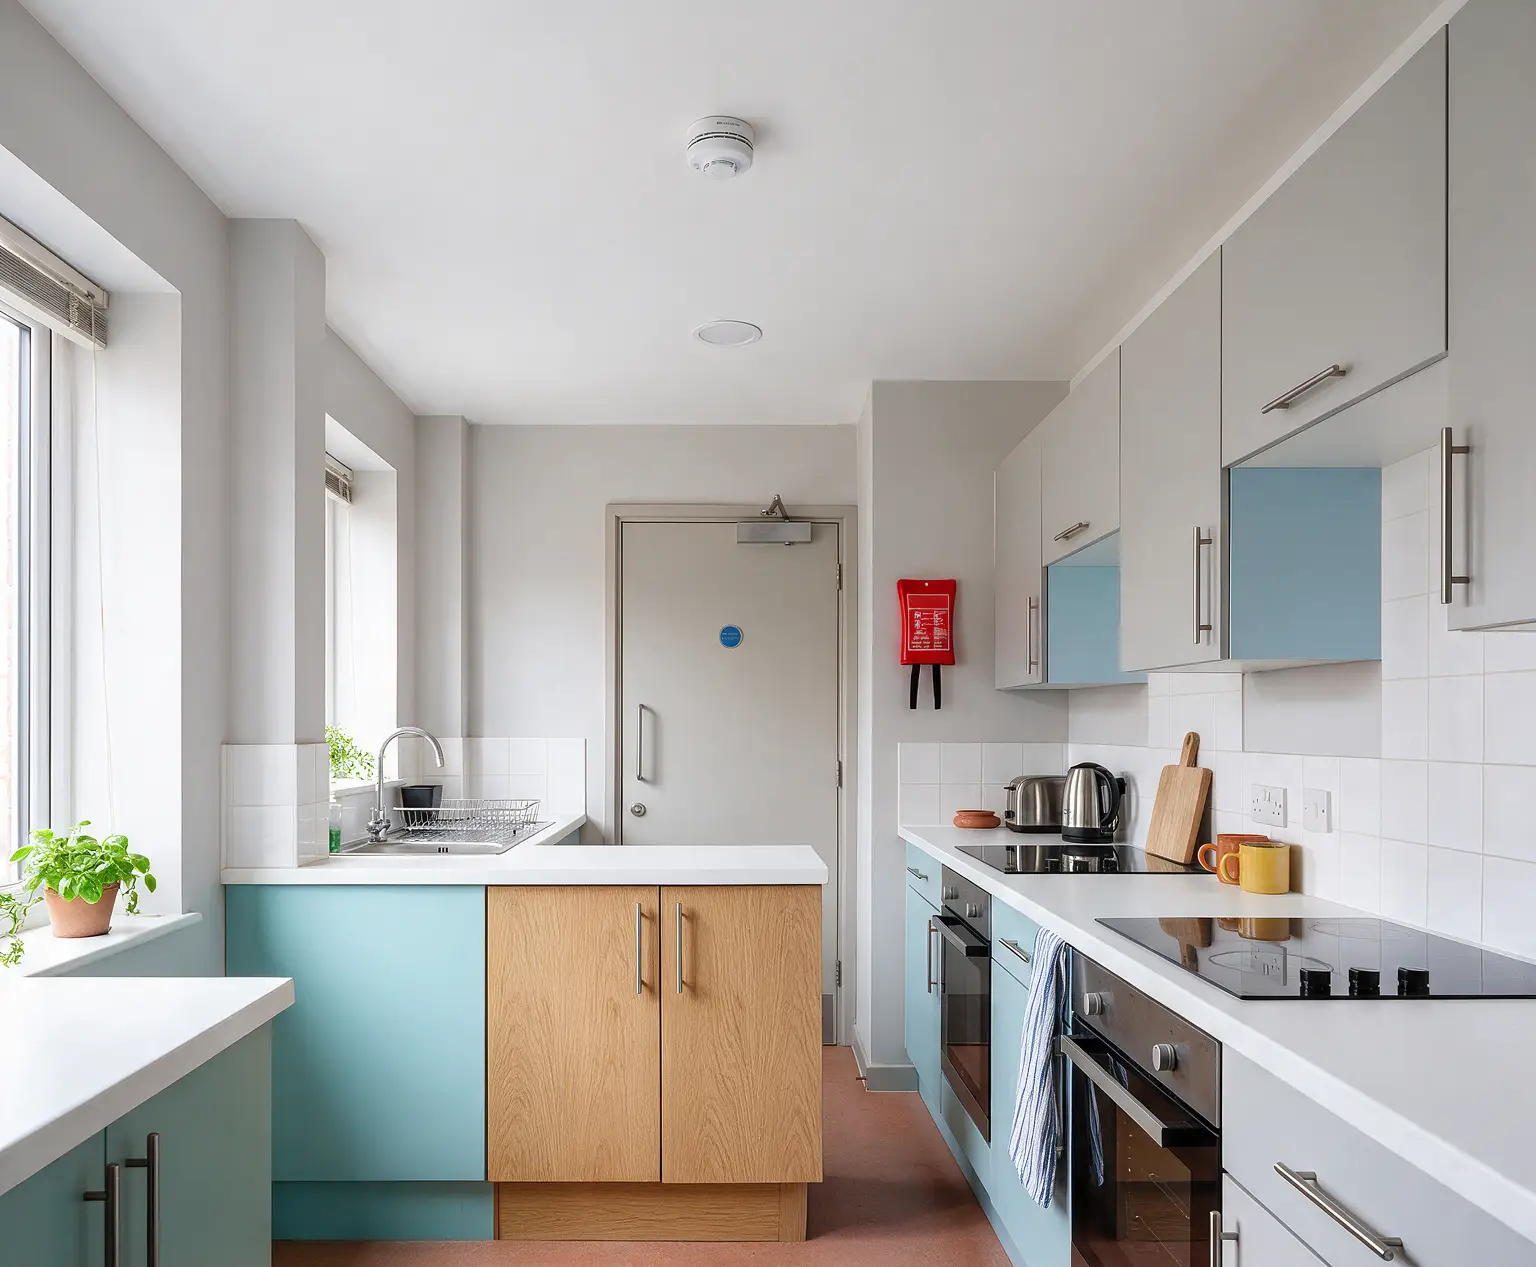
- Fire safety equipment, often £1,000 to £3,000
- Furnishings, often £800 to £1,500 per room
- The licence fee
- Any work needed to meet room size, fire safety or amenity standards
Running costs are higher as well. Bills are often included in the rent, which leaves energy costs with you. Management typically costs 10% to 15% of rent, because there are several tenants, more maintenance and more compliance to handle. Wear and tear is heavier in a shared house, and rooms can sit empty between tenants. A void allowance of 4% to 8% of annual rent is a sensible starting point, with more in student areas where summer vacancies are common.
HMO Rental Yields
An HMO earns more because you let by the room. A four-bedroom house that rents for £1,200 a month as a single let might produce £2,000 to £2,400 as an HMO. Room rents depend heavily on the area, often £400 to £600 a month in regional cities and £600 to £900 in parts of London, and an en-suite or larger room can add £75 to £150.
Gross yield is the headline figure, but net income is what pays the mortgage. Take a five-room house at £500 a room:
- Gross rent: £2,500 a month, or £30,000 a year
- Voids at 6%: £1,800
- Management at 12%: £3,600
- Bills, maintenance and compliance: around £5,000
- Income before mortgage and tax: about £19,600
These figures are illustrative. Your own rents and costs will differ, and the mortgage payment comes off the final line. The HMO mortgage calculator shows how a given loan fits against rental income.
Location drives the rest. Properties near universities, hospitals and employment centres tend to let easily, with rents often 15% to 20% higher. Converting a spare reception room into a bedroom can add income, but you need to keep enough communal space to stay within the council’s standards.
Managing an HMO
An HMO needs more hands-on management than a standard let. Rent collection, repairs and cleaning of shared areas all need a system, and a visit every quarter at minimum catches problems early. Written house rules covering noise, cleaning and visitors prevent most disputes, and a professional cleaner for communal areas usually earns its fee back in larger houses.
Turnover is the main operational risk. Careful tenant vetting and a comfortable, well-kept house keep people longer, which cuts voids and re-letting costs. Many landlords also join an accreditation scheme or a landlord association such as the National Residential Landlords Association for training and regulation news, and lenders and councils both view that favourably.
How HMO Finance Works at a Glance
HMOs are usually financed through specialist lenders, because many mainstream lenders will not touch them. The terms are tighter than for standard buy-to-let:
- A deposit of at least 25% is typical, with loan-to-value up to 75% and up to 80% from some specialist lenders
- Interest rates are normally higher than on a standard buy-to-let
- Lenders assess rental income rather than your salary, usually asking for rent to cover 125% to 145% of the mortgage payment at a stressed interest rate
- Most lenders want to see landlord experience, often a year or more of buy-to-let
- The property must hold a valid licence and the correct planning consent
Valuation can also differ. Some lenders value an HMO on a bricks-and-mortar basis and others on the income it produces, which can move the amount you can borrow by a large margin. Current pricing is on our HMO mortgage rates page, and our HMO finance service page explains how each of these tests works in full.
How a Broker Helps With HMO Finance
HMO lenders differ widely on property type, number of rooms, tenant mix and borrower experience. One lender’s decline can be another lender’s routine approval. A broker who works across the HMO panel can tell you which lenders are likely to accept your property, what loan-to-value and rate to expect, and how to present the application before anything is submitted, which protects your credit file from avoidable declines.
Frequently Asked Questions
What deposit do I need for an HMO mortgage?
Most HMO lenders ask for a deposit of at least 25% of the property value. Some specialist lenders will go to 80% loan-to-value, but a larger deposit gives you a wider choice of lenders and better rates.
How much does an HMO licence cost?
It depends on the council. Fees are set locally and often run from several hundred pounds to over £1,000, and some councils charge more for larger HMOs. A licence usually lasts up to five years, which spreads the cost over that period.
How many tenants make a property an HMO?
Three or more people from more than one household sharing a kitchen, bathroom or toilet make a property an HMO. A single family living together counts as one household. A family of five is not an HMO, while three unrelated sharers are.
Are bills usually included in HMO rent?
Often, yes. Many landlords include energy, water and broadband in the rent because it simplifies life for tenants and avoids arguments over splitting bills. You carry the usage risk, and a fair-use clause in the tenancy agreement helps.
Will I need planning consent to turn a house into an HMO?
Not always. In England, moving from a standard home to a small HMO is normally permitted development, but councils with an Article 4 Direction require a planning application, and larger HMOs for seven or more people always need planning permission. Check with the local planning authority before you buy.
How much can an HMO earn compared with a standard buy-to-let?
An HMO can earn well above the same house let to one household, since rent is charged per room. After bills, management, voids and compliance costs, the net gain is smaller than the headline figure. Work from net income.
What is the difference between a small and a large HMO?
A small HMO has three or four occupants from more than one household, and a large HMO has five or more. In England the large ones always need a council licence, while the smaller ones only need one where the council runs an additional scheme.
Speak to a Specialist
Speak to a specialist commercial finance broker before you apply.
Commercial Finance Network is directly authorised and regulated by the Financial Conduct Authority. HMO and other business finance is not regulated by the Financial Conduct Authority. Your property may be repossessed if you do not keep up repayments on a loan secured against it.
Call us on 03303 112 646 / 01494 622 111 or email info@cfnuk.com to discuss HMO finance for your property.
Related Pages
- HMO Finance – our HMO mortgage service for purchases and refinancing.
- HMO Mortgage Rates – current rates, fees and what sets your rate.
- HMO Mortgage Calculator – borrowing capacity and rental coverage for purchase and remortgage.
- HMO Remortgages – release equity or move to a better rate on an existing HMO.
- Why Some HMOs Cannot Be Financed – the reasons strong-looking deals still get declined.
- Funding an HMO Conversion – how bridging and term finance work together across a conversion.

